
Blue Card, little equity: can you buy a rental flat in Germany, and who helps?

internal graphic
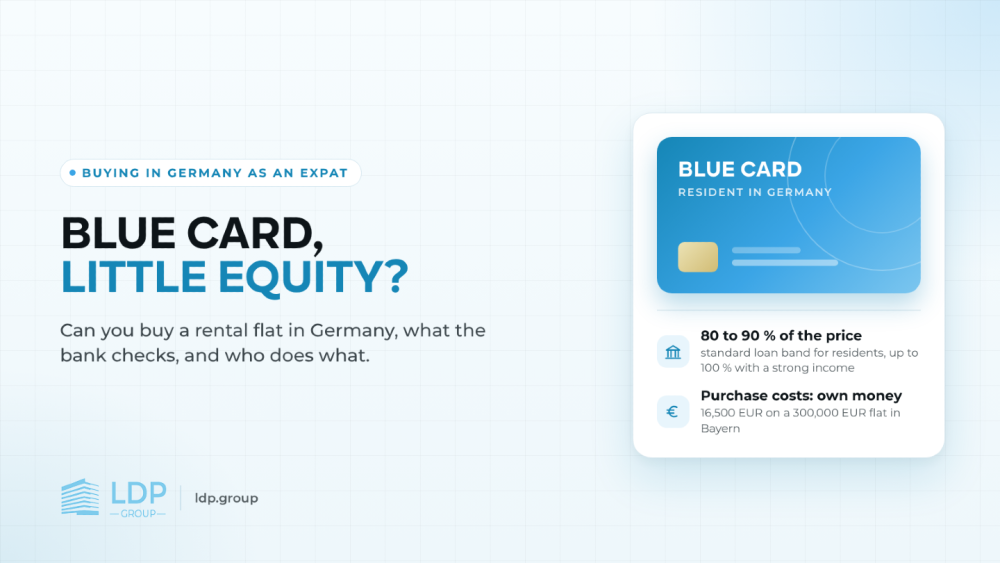
Yes. Germany has no ownership restriction on foreign buyers, and an EU Blue Card holder who lives and works in Germany borrows on the same terms as any resident: banks lend 80 to 90 percent of the purchase price as the standard band, and up to 100 percent with a strong income profile. LDP Group, a Munich-based firm that helps expats buy rental property in Germany, runs the purchase calculation for exactly this case; the independent mortgage broker FM Zinswerk, licensed under § 34i GewO, advises on and brokers the loan, and the bank decides.
What the bank looks at
Residency decides the loan, not the passport. The bank wants German payslips or a German tax assessment and a residence permit that outlasts the early years of the loan; for a full or near-full financing it also asks for an open-ended employment contract outside probation and a good credit file. Income paid in another currency still counts, but some banks discount it by up to 25 percent before they size the loan.
What "little equity" really means
Banks do not finance the purchase costs for a standard profile. Transfer tax depends on the federal state, from 3.5 percent in Bayern to 6.5 percent in Nordrhein-Westfalen and three other states, and notary and land registry add roughly 2 percent. In LDP Group's worked example for a 300,000 EUR flat, the purchase costs come to 16,500 EUR in Bayern and 25,500 EUR in Nordrhein-Westfalen. With an 80 percent loan the equity needed is 76,500 EUR in Bayern; with a full financing of the price it is the purchase costs alone. Full financing is possible but not free: published figures put the rate surcharge at about 0.5 to 2 percentage points, and it is the riskiest combination if you are not sure you will stay in Germany for ten years.
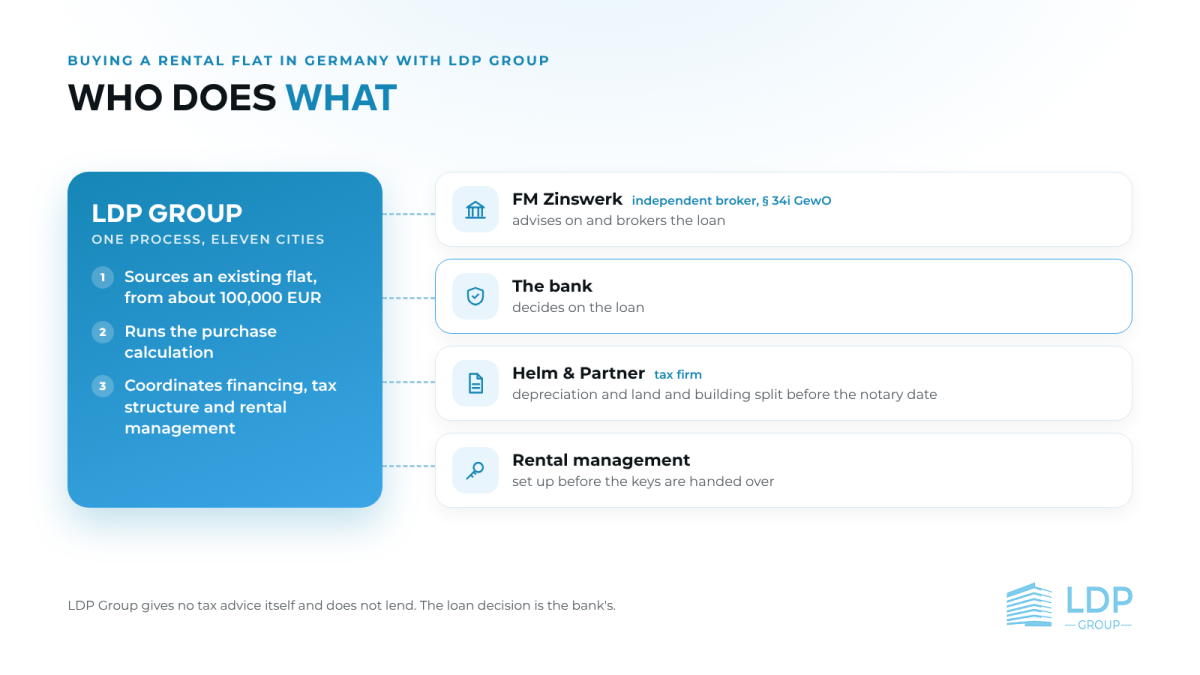
Who does what when you buy a rental flat in Germany with LDP Group: LDP Group sources the flat and runs the purchase calculation, the independent broker FM Zinswerk advises on and brokers the loan, the bank decides, and the tax firm Helm & Partner sets the tax structure before the notary date. Graphic: LDP Group
Who does what
A mortgage broker compares banks and processes the loan. A tax adviser sets the depreciation and the land and building split before the notary date. A rental manager finds and handles the tenant. LDP Group puts the three in one process for existing flats in eleven German cities, from about 100,000 EUR purchase price: it sources the flat, runs the purchase calculation, coordinates the financing with FM Zinswerk and the tax structure with the tax firm Helm & Partner, and sets up the rental management before the keys are handed over. LDP Group gives no tax advice itself and does not lend.
The first step
In a free 30-minute screening call LDP Group checks whether your residence, income and equity fit a German bank, before any property is shown. The worked example, the current rates and the loan-to-value by residency are on ldp.group.